Disclaimer: Views in this blog do not promote, and are not directly connected to any L&G product or service. Views are from a range of L&G investment professionals, may be specific to an author’s particular investment region or desk, and do not necessarily reflect the views of L&G. For investment professionals only.
Why this Fed hiking cycle may not matter
Our take: It may restore Fed credibility, but it is unlikely to materially change the inflation or economic backdrop, creating potential opportunities for investors.
Markets are once again focused on the Federal Reserve. The Fed last week raised rates for the first time since 2023, inflation is still above target, and investors are debating whether one hike becomes two, three or more, with four hikes currently priced in. But the bigger question is whether this particular hiking cycle is likely to matter for inflation or the economy. Our take: It may restore Fed credibility, but it is unlikely to materially change the inflation or economic backdrop, creating potential opportunities for investors.
Upside inflation risk ebbs and builds with oil
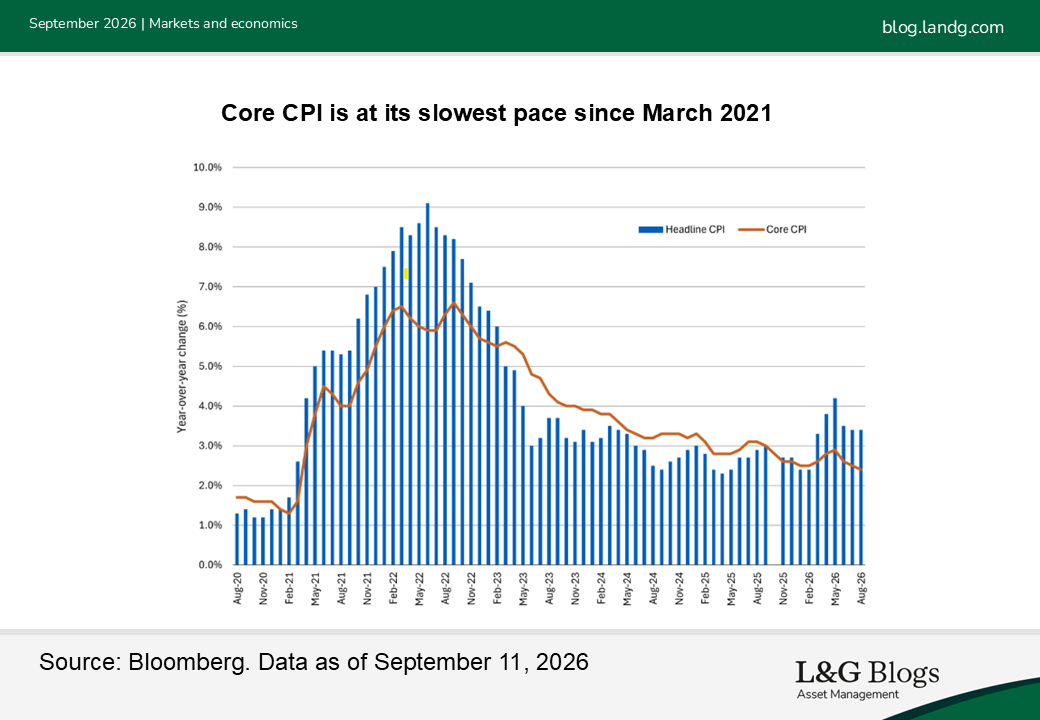
The case for rate hikes rests on the Fed’s price-stability mandate, but the composition of inflation matters. While core CPI surprised to the upside in August, it has continued to normalize, as evident in the chart below, while the recent renewed inflation concern has been tied more closely to energy and geopolitical disruption. That distinction is important. Rate hikes typically work by restraining demand. They are likely to be much less effective when the marginal inflation impulse comes from supply, particularly an energy shock linked to the Gulf conflict.
A quarter-point move, or even a small sequence of moves, is unlikely to do much to the price of oil. To materially affect supply-driven inflation through demand destruction, the Fed would likely need to tighten enough to create a broader economic slowdown. That is not our, or the market’s, base case.
The economy is less rate-sensitive than the market narrative suggests
The economy also looks less vulnerable to a modest hiking cycle than in prior regimes. The post-global-financial-crisis expansion was defined by private-sector deleveraging, low nominal growth and a policy rate pinned near zero. Today’s backdrop is different.
Nominal growth is firmer, public-sector leverage is doing more of the heavy lifting, corporate balance sheets are not broadly retrenching and AI-related investment remains a powerful source of capex demand.
Financial conditions reinforce that point. Even with the policy rate well above the zero-bound era, broad conditions remain accommodative enough to support activity, with financial conditions as loose as they have been at any point this century.[1] In such an environment, it likely takes more than a handful of hikes to meaningfully alter growth. A few additional hikes are unlikely to break an economy supported by fiscal policy, AI-related business investment, resilient consumers and still-loose financial conditions.
A small hiking cycle can still matter to markets — because markets think it matters
The nuance is that markets can move on a story even if the story does not ultimately change the economy. With less forward guidance, each meeting can produce larger moves and more surprises. That makes the Fed relevant for volatility, even if it is less relevant for the medium-term macro outcome.
In our view, this distinction creates opportunity and reinforces the case for dynamic duration management. If investors price in a sustained tightening cycle, risk assets may cheapen on a move that does not materially change inflation or growth, given that the hurdle for a Fed-driven macro break is higher than markets may assume. If the inflation impulse fades as energy stabilizes, the Fed could ultimately reverse course next year before the full effect of hikes is ever felt.
In that case, we would view weakness related to the rate story as a potential opportunity. More broadly, if the most bearish narratives do not worsen — or if some, such as the Gulf conflict or energy shock, resolve — there may be room for risk assets to rally even in the presence of a modest hiking cycle. We would be more concerned if inflation broadened from energy into wages and core services, if financial conditions tightened meaningfully, or if markets began pricing a terminal rate well beyond what is needed. But absent that combination, modest tightening may prove more important for market pricing and volatility than for the medium-term growth and inflation outlook.
Disclosures
Unless otherwise stated, references herein to "L&G" and “L&G – Asset Management” refer to the global asset management business of Legal & General Group plc. that includes Legal & General Investment Management Ltd. (a U.K. FCA authorized adviser), Legal & General Investment Management America, Inc. (a U.S. SEC registered investment adviser) Legal & General Investment Management Asia Limited (a Hong Kong SFC registered adviser), Legal & General Investment Management Japan KK (licensed by the FAS in Japan), and LGIM Singapore Pte. Ltd. (licensed by the MAS in Singapore). The LGIM Stewardship Team acts on behalf of all such locally authorized entities.
This material is intended to provide only general educational information and market commentary. Views and opinions expressed herein are as of the date set forth above and may change based on market and other conditions. The material may not be reproduced or distributed. The material is for informational purposes only and is not intended as a solicitation to buy or sell any securities or other financial instrument or to provide any investment advice or service. L&G – Asset Management, America does not guarantee the timeliness, sequence, accuracy or completeness of information included. Past performance should not be taken as an indication or guarantee of future performance and no representation, express or implied, is made regarding future performance.
Certain of the information contained herein represents or is based on forward-looking statements or information, including descriptions of anticipated market changes and expectations of future activity. Forward-looking statements and information are inherently uncertain and actual events or results may differ from those projected. Therefore, undue reliance should not be placed on such forward-looking statements and information. There is no guarantee that L&G – Asset Management, America’s investment or risk management processes will be successful.
[1] Source: L&G – Asset Management Americas Research, Bloomberg. Data as of September 15, 2026
Recommended content for you
Learn more about our business
We are one of the world's largest asset managers, with capabilities across asset classes to meet our clients' objectives and a longstanding commitment to responsible investing.