Disclaimer: Views in this blog do not promote, and are not directly connected to any L&G product or service. Views are from a range of L&G investment professionals, may be specific to an author’s particular investment region or desk, and do not necessarily reflect the views of L&G. For investment professionals only.
UK equities: political churn, corporate conviction
Despite political and economic uncertainty in the UK, companies continue to report strong earnings and trade at potentially attractive free cashflow multiples, as evidenced by increased M&A activity.

A new political risk premium?
With the UK’s seventh prime minister since 2016 taking office, investors could be forgiven for asking whether political churn itself has become part of the UK equity risk premium. Andy Burnham has reshuffled the cabinet and arranged his advisers, yet full detail on policy agenda and interpretations of his “pro-business” stance is still taking shape.
This creates an overhang for UK equities. Until more clarity emerges, the market is being asked to price a leadership transition, an approaching Autumn Budget and a fiscal backdrop that leaves limited room for manoeuvre.
Burnham has committed to maintain Labour’s existing fiscal rules set out by Keir Starmer and former Chancellor Rachel Reeves, which is helpful from a market-stability perspective. Likewise, the selection of the new Chancellor, John Healey, was reportedly viewed[1] as one of the more market-friendly options. The tougher question is how the government can fund new policy priorities while still subject to the confines of its fiscal rules.
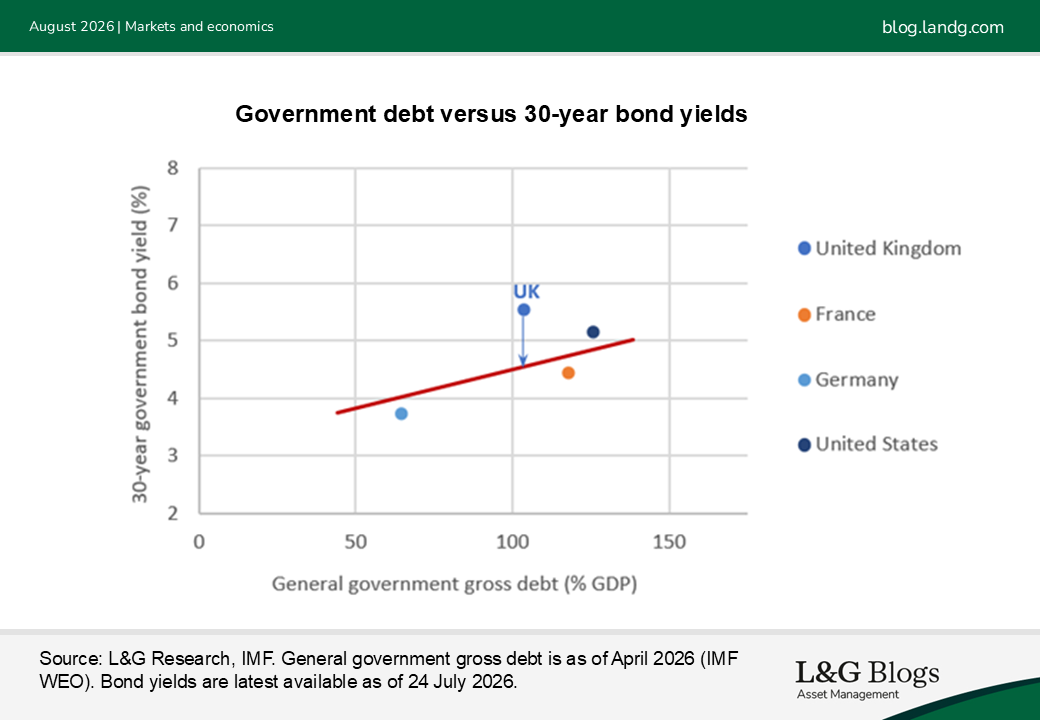
Ideally, the UK would be on a trajectory to lower public sector net debt relative to GDP, given its elevated borrowing costs. Yet as shown below, there is already uncertainty baked into UK bond yields relative to the rest of the world, particularly its G7 peers. As markets wait for Burnham to chart his course, investors are likely to remain cautious on the most domestically exposed parts of the market, particularly in areas where changes in policy, tax or regulation could directly affect earnings.
M&A provides a different signal
Political uncertainty is not the only tide moving UK equities. M&A activity has picked up materially in 2026, with the value of offers for UK companies rising sharply compared with the same date last year and exceeding $90 billion[2].
Foreign buyers have been at the helm of this activity, accounting for the overwhelming majority of UK deal value, with US acquirers responsible for more than half of overseas bids.[3] This suggests that while domestic public market investors have remained cautious, strategic or financial buyers are increasingly willing to take aim at UK assets where they see durable cash generation, resilient balance sheets and valuations that remain adrift from comparable opportunities elsewhere.
What is particularly interesting to observe in our view is that in 2026 the deal activity so far has been dominated by global strategic buyers while mid-market private equity firms have kept their powder dry compared to previous years.[4]
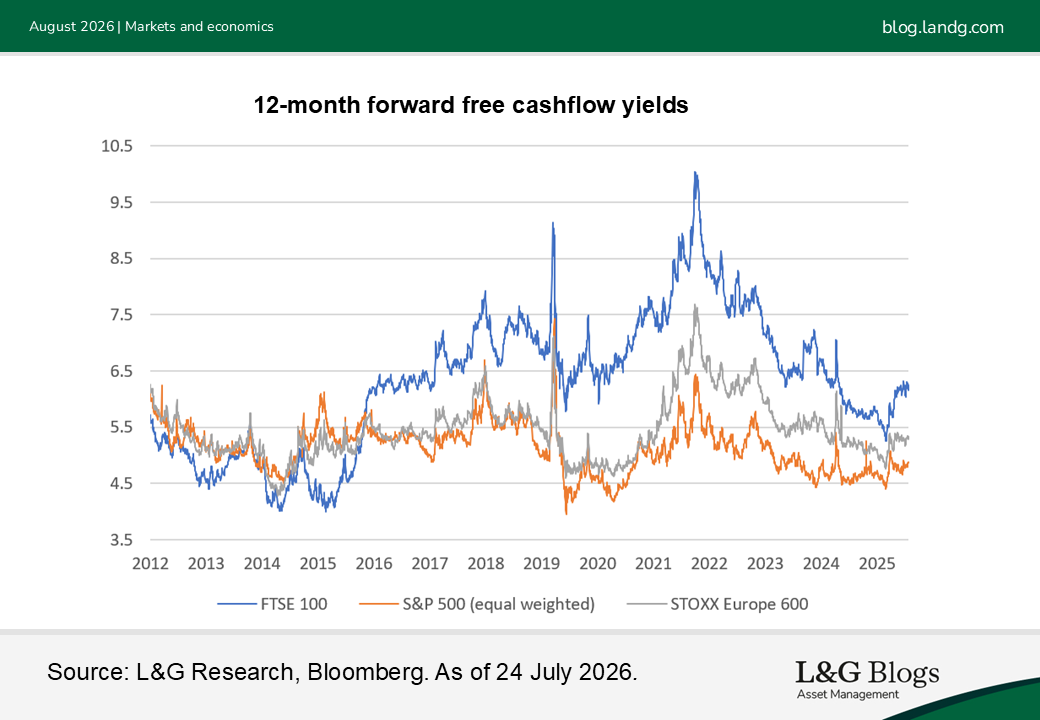
The main current behind the renewed bid interest is this persistent valuation disconnect between US and European markets, and between UK public market prices and private market assessments of value. The UK continues to screen as one of the cheapest regions on a free cashflow yield basis, as depicted by the chart below. For overseas corporates and private equity buyers, this creates a favourable crossing: the opportunity to acquire established, cash-generative businesses at valuations that remain meaningfully below those available in their home markets.
A vote of confidence in UK assets
We have long argued that UK valuations are low relative to fundamental earnings quality. The message from the deal market is clear: where public markets are reluctant to re-rate UK equities, corporate buyers and private capital are increasingly prepared to do so instead.
This does not remove the political and macroeconomic headwinds, but it does potentially provide an important valuation buoy.
As long as the transatlantic valuation gap remains wide, we believe selected UK companies are likely to stay on the radar of bidders looking to navigate toward quality assets at potentially attractive entry prices.
* For illustrative purposes only. Reference to a particular security is on a historic basis and does not mean that the security is currently held or will be held within an L&G portfolio. The above information does not constitute a recommendation to buy or sell any security. Assumptions, opinions, and estimates are provided for illustrative purposes only. There is no guarantee that any forecasts made will come to pass.
[1] Bloomberg Markets Live Pulse Survey
[2]Deutsche Bank, as of 07/08/2026. Includes confirmed and announced potential offers.
[3] Reuters, May 2026
[4] Peel Hunt, June 2026: UK Takeover Trends, H1 2026 review
Recommended content for you
Learn more about our business
We are one of the world's largest asset managers, with capabilities across asset classes to meet our clients' objectives and a longstanding commitment to responsible investing.